Startup Profitability: ROI, ROIC, Payback and Unit Economics Without the Confusion
High revenue doesn't mean high return. This guide separates profitability from return on investment, shows how to calculate ROI, ROIC, payback and contribution margin, explains which unit economics metrics really matter in SaaS and services, and delivers a checklist to decide where to reinvest every dollar of cash. Find out why high-revenue companies still fail, how to spot the financial bottleneck before it shows up on your bank statement, and which concrete levers increase profitability without compromising growth.
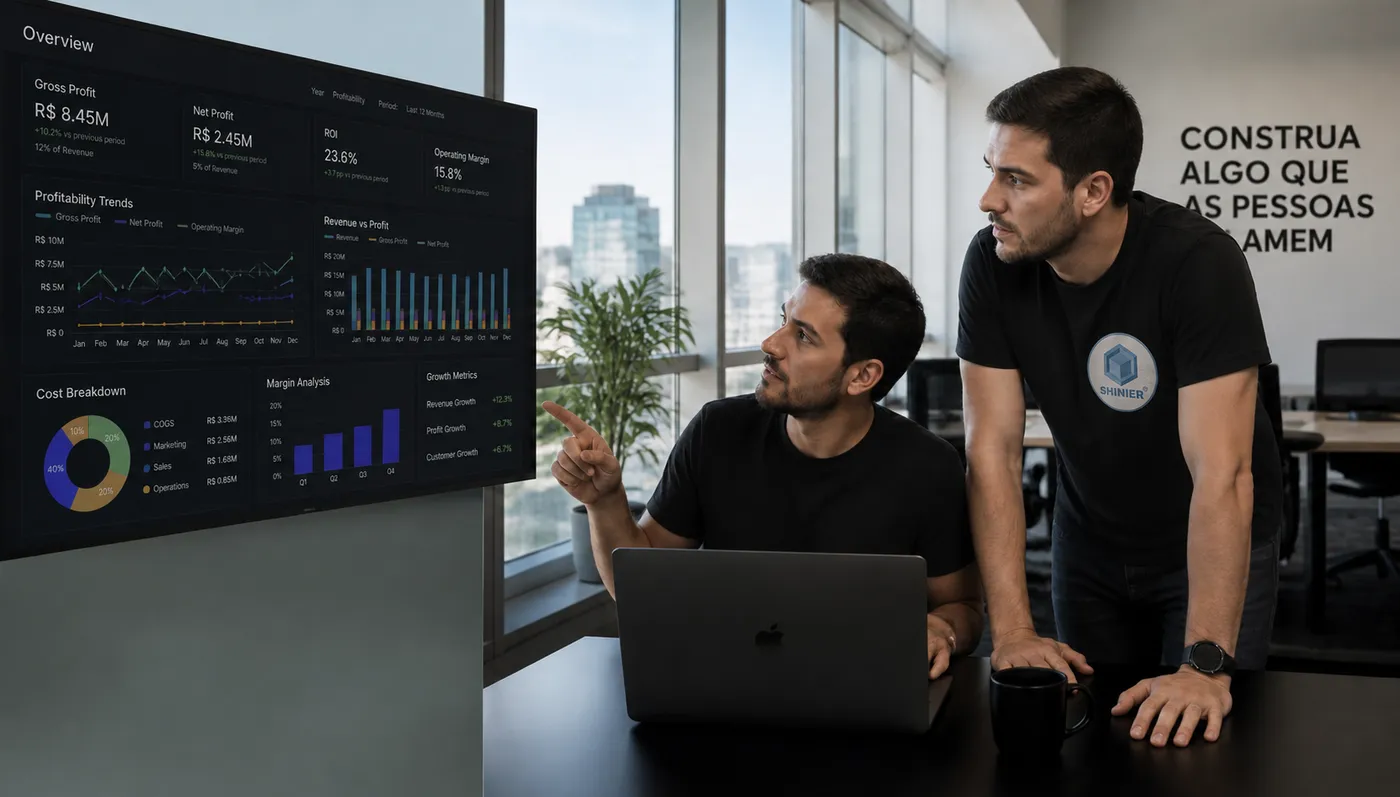
There is a moment in the life of almost every startup when revenue goes up, the team grows, the sales dashboard looks beautiful — and cash remains tight. When this happens, the problem is rarely about selling too little. It's about confusing profit margin with return on investment (profitability) and making reinvestment decisions without knowing how much each applied dollar actually returns.
Profitability is the most uncomfortable question a board can ask: given everything that has already been put into this operation — equity, venture capital, debt, founders' time — how much does this money yield per year, and does this yield compensate for the risk taken? Aswath Damodaran summarizes the criteria in a single sentence: return without comparison to the cost of capital is just a loose number.
This guide covers the complete path. First, it separates profit margin from return on investment. Then, you use a simulator with an AI assistant that asks questions and calculates in real time ROI, ROIC, payback, contribution margin, LTV/CAC and your business's Rule of 40. Next, we dive into unit economics, the relationship between return, risk and time, the cases where growing reduces profitability, an example of analysis by product, customer and channel, and a final checklist to decide where to put your cash.
💡 The most expensive mistake: celebrating revenue growth without looking at how much capital was consumed to produce it. Doubling in size while burning three times more cash isn't scale — it's a bet with an expiration date.
What is the difference between profit margin and return on investment?
Profit margin answers: of every dollar sold, how much is left? It's a measure of operational efficiency, expressed as a margin. Return on investment answers: of every dollar invested, how much comes back per year? It's a measure of capital efficiency, expressed as a rate of return. The two walk together, but one does not guarantee the other.
An example makes the difference concrete. A consulting firm with $100k in monthly revenue and a 20% net margin generates $240k of profit per year. If the operation required $300k of capital, the return is 80% per year — extraordinary. If it required $4 million in infrastructure, platform and inventory, the same 20% margin produces only a 6% return, below any government bond. Same profit, completely different businesses.
Profit Margin (Lucrativeness)
Profit ÷ revenue. Shows the health of the pricing model and cost control. Improves with price increases, variable cost reduction and fixed cost dilution.
Return on Investment (Profitability)
Profit ÷ invested capital. Shows whether it's worth keeping the money in this business instead of allocating it to another project, product or investment.
Simulate your business profitability right now
Chat with the assistant below. With every answer you provide, the dashboard fields are filled in and the calculations — contribution margin, profit, ROI, ROIC, payback, LTV/CAC and Rule of 40 — are recalculated on the fly. The more information you provide, the more accurate the diagnosis becomes.
Analista de rentabilidade Shinier
Ao informar e-mail e WhatsApp você concorda em receber o diagnóstico da Shinier. Seus dados não são compartilhados com terceiros.
Sua simulação
0/8 camposReceita mensal
—
Custos variáveis
—
Custos fixos mensais
—
Capital investido
—
Ticket médio por cliente
—
CAC (custo de aquisição)
—
Churn mensal
—
Crescimento anual
—
Transform these numbers into reinvestment decisions
Knowing the ROI is just the beginning; the real value appears when this number guides where to put your next dollar. This is exactly the work we do alongside founders and software house managers every day.
For founders building from scratch
Set up your pricing, cash flow, and projections with AI-guided tools and discover which channels yield the highest return for your capital.
For enterprises and software houses
Need to visualize profitability by project, client, and squad before hiring your next team? Talk to the Shinier team.
How to calculate the financial indicators from the simulator?
Each of the indicators calculated in the simulator answers a specific question about the health and efficiency of your business. Capital and operating metrics should be analyzed together: in isolation, any of them can mask severe risks.
Contribution Margin
(Revenue − Variable Costs) ÷ RevenueMeasures the percentage of revenue that remains from each sale to cover fixed costs and generate profit. It is the basis for breakeven and pricing.
Operating Profit and Net Margin
Profit = CM ($) − Fixed | Margin = Profit ÷ RevenueOperating profit is the monthly result of the operation. Net margin indicates what percentage of revenue actually became financial surplus.
ROI — Return on Investment
(Annualized Gain − Investment) ÷ InvestmentMeasures how much a specific investment returned relative to the applied amount. Ideal for comparing discrete projects, such as campaigns or acquisitions.
ROIC — Return on Invested Capital
NOPAT ÷ (Equity + Interest-Bearing Debt − Cash)Measures the percentage profitability of the operation over all capital tied up in the business, using NOPAT (after-tax profit) to isolate debt distortions.
Investment Payback
Invested Capital ÷ Monthly Operating ProfitIndicates in how many months the accumulated profit returns the initial invested capital. Essential for evaluating cash runway needs.
Practical interpretation of the numbers
Consider a startup with $180k/month in revenue, 75% contribution margin and $96k in fixed costs. This leaves $39k/month in operating profit (21.7% net margin), totaling $468k per year.
If the company required $1.5 million of invested capital, the gross return (ROI) is 31.2% per year. However, to know if this return compensates for the risk and exceeds the cost of capital, we need to adjust the result for operational taxes (NOPAT) and calculate ROIC — detailed in the next section.
In addition, the 38-month payback warns that, in bootstrapped operations, the company needs sufficient cash reserves to cross the maturation period without compromising survival.
What is NOPAT and why is it the key to real profitability?
NOPAT (Net Operating Profit After Taxes) is the definitive indicator that connects the operation's result to the real return on capital (ROIC), without debt or tax distortions.
1. Isolates Operating Performance
Eliminates loan interest and financial revenues to purely measure the operation's cash-generating capacity.
2. Applies Real Tax Adjustment
Deducts the direct taxes required on the operation. Without this adjustment, the return would be artificially inflated.
3. It is the Exact ROIC Numerator
In the formula ROIC = NOPAT ÷ Invested Capital, using accounting net income would distort the return by double-counting financial expenses.
Formula and practical application of NOPAT
In the Shinier simulator, applying an estimated 34% rate (multiplying by 0.66) on the annual operating profit of $468k, the real NOPAT is $308,880. Dividing this amount by the invested capital of $1.5 million, we get a net ROIC of 20.6% per year.
Which unit economics metrics matter in SaaS and services?
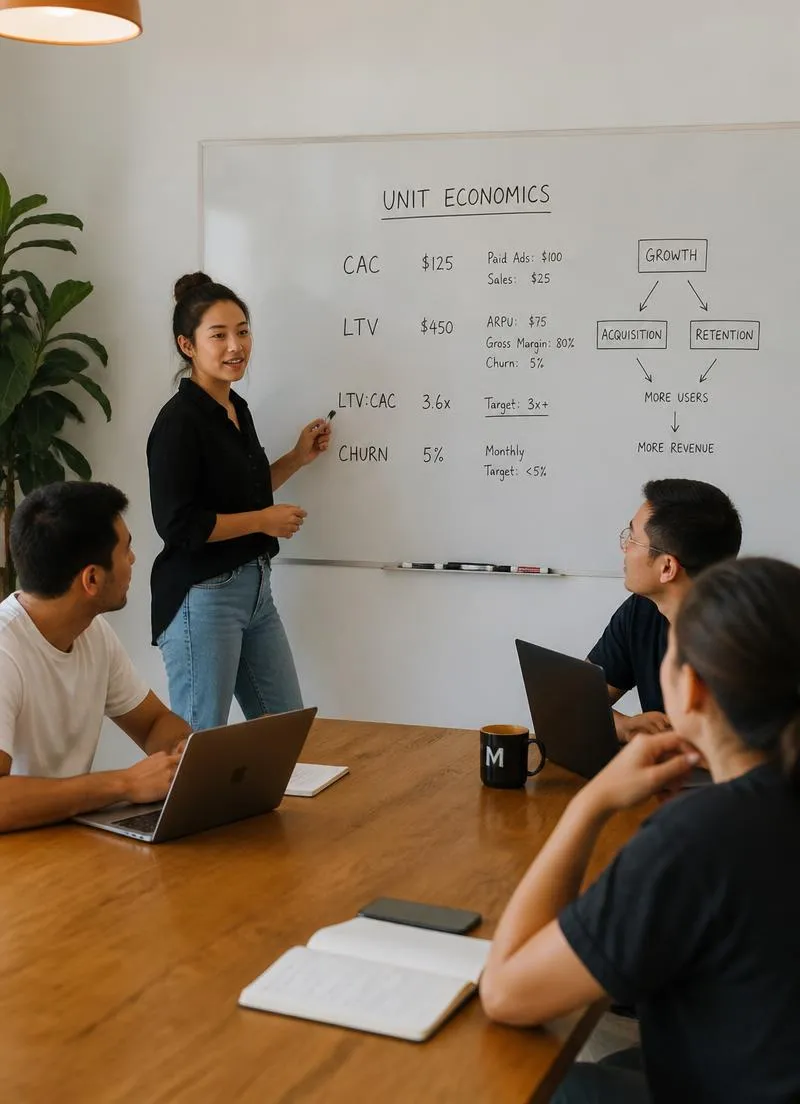
Unit economics reduces the company to a repeatable unit — a customer, a subscription, or a project — to verify if that unit generates sustainable value before accelerating sales.
Below are the four unit economics metrics calculated in the simulator:
LTV — Lifetime Value
LTV = Monthly Contribution Margin per Customer ÷ Monthly ChurnLTV measures the accumulated value a customer generates throughout the entire period they remain with the company. It should always be calculated using contribution margin (never gross revenue), divided by the monthly churn rate.
LTV / CAC — Acquisition Efficiency
LTV/CAC Ratio = LTV (in margin) ÷ CAC (Customer Acquisition Cost)Indicates how many times the value returned by a customer exceeds the cost invested in marketing and sales to acquire them. The market benchmark is 3x or more. Below 2x, growth consumes more cash than it generates.
CAC Payback — Recovery Pace
CAC Payback = CAC ÷ Monthly Contribution Margin per CustomerCalculates in how many months the margin generated by the customer pays for the cost invested to bring them in. In B2B SaaS, a payback under 12 months allows for self-funded growth; above 18 months requires external capital.
Rule of 40
Rule of 40 = Annual Growth Rate % + Net Margin %Popularized by Bessemer Venture Partners, it evaluates the balance between expansion speed and profitability. It adds the revenue growth percentage to the net margin. A result equal to or greater than 40 indicates excellent efficiency.
Services and Software Houses: adapting unit economics
In services and software consulting companies, the repeatable unit is the project or the allocated hour. The equivalent metrics are team utilization rate, average hourly rate charged, direct cost per developer/squad, and gross margin per contract.
Net Dollar Retention (NDR)
Net retention above 100% means that the current customer base spends more each year (expansion exceeds cancellations). It is the biggest profitability multiplier in SaaS because it generates additional revenue with zero CAC.
📌 Compare with real peers: SaaS Capital's benchmarks for private companies show very different ranges from public companies. Comparing your operation with a listed unicorn is the fastest path to unrealistic goals and misguided capital decisions.
How to compare financial return with risk and timeframe?
No rate of return means anything on its own. Damodaran organizes the comparison into three axes: how much it yields, with what degree of uncertainty, and in how much time. A project with a 25% expected return and a high probability of failure might be worth less than one with an almost certain 14% — and an excellent return that only materializes in four years might be unviable for someone with twelve months of cash runway.
| Allocation | Expected Return | Risk | Time to Return |
|---|---|---|---|
| Reduce churn from current base | Very high per dollar applied | Low | 1 to 3 months |
| Increase price on new cohorts | High | Medium | Immediate |
| Scale validated acquisition channel | Medium to high | Medium | 6 to 12 months |
| Open new product line | Potentially high | High | 12 to 24 months |
| Hire team ahead of demand | Low | High | Undefined |
The table explains why retention is almost always the most profitable allocation for an early-stage startup: the return appears quickly, the risk is low, and the compounding effect on LTV improves all other numbers at the same time. Even so, it is the initiative that most frequently loses the internal dispute to new campaigns, because top-of-funnel growth is more visible than avoided churn.
When does growing reduce business profitability?
Growth consumes cash before it returns it. This is normal and expected. The warning sign is when unit indicators worsen as the company grows — a sign that scale is not creating efficiency, just volume.
CAC rises faster than average ticket
Saturation of the main channel or entry into segments with lower willingness to pay. When this happens, each new cohort has a longer payback than the previous one and aggregate profitability falls even with growing revenue.
Contribution margin shrinks with volume
Costs that seemed fixed reveal themselves to be variable: support per customer, infrastructure per use, sales customizations. If every new contract requires adaptation, the business is selling a service at a product price.
Fixed costs grow in steps before revenue
Hiring and structure come in all at once, revenue comes in gradually. This is a legitimate effect, but it requires cash planning: whoever hires in steps needs to know how many months of planned losses they can sustain.
Churn increases with the base
A sign that acquisition is bringing in customers outside the ideal profile. Growing with increasing churn is filling a leaky bucket with a bigger hose — costs rise, LTV falls, and profitability plummets.
Example analysis by product, customer and acquisition channel
Average profitability is deceiving. The math only becomes a decision when you break the result down into three cuts: what you sell, who you sell to, and how you acquire them. The table below is a typical cut of an operation with $180k in monthly revenue.
| Segment | Monthly Revenue | Contribution Margin | CAC | CAC Payback |
|---|---|---|---|---|
| Product — self-service plan | $54,000 | 82% | $340 | 4 months |
| Product — enterprise plan | $96,000 | 61% | $7,800 | 11 months |
| Product — on-demand customizations | $30,000 | 28% | — | — |
| Customer — small businesses | $72,000 | 78% | $520 | 5 months |
| Customer — industry | $108,000 | 56% | $6,100 | 13 months |
| Channel — organic search and content | $66,000 | 80% | $190 | 2 months |
| Channel — paid media | $48,000 | 72% | $1,450 | 9 months |
| Channel — customer referrals | $66,000 | 79% | $120 | 1 month |
What this table tells you to do
On-demand customizations account for 17% of revenue and less than 7% of margin — they consume senior time and stall the roadmap. The decision isn't necessarily to close the line, but to reprice it or turn it into a configurable product.
Referrals and organic content have the lowest CAC and shortest payback, but together account for 73% of revenue: high dependence on channels that are hard to accelerate on demand. The correct read is to reinvest to expand the capacity of these channels before increasing paid media.
The industry segment has a lower margin and a 13-month payback, but it tends to have much lower churn. Before cutting it, calculate the LTV per segment — low margin with years of retention can be more profitable than high margin with quarterly turnover.
Checklist to decide where to reinvest cash
Run these eight questions before approving any significant capital allocation. If three answers are negative, the decision needs to go back to the drawing board.
What is the expected return and in what timeframe?
Without a number and a timeframe, it's not an investment decision — it's an intention. Write down the estimate before spending.
Does this return exceed the cost of capital?
If money costs 15% per year and the project yields 11%, you are destroying value even with positive accounting profit.
Does the payback fit into the cash reserve?
A project with a return in 30 months and cash for 10 is not ambitious, it's insolvent. Adjust the size of the bet to your real runway.
Is the unit contribution margin positive?
Scaling a unit with a negative margin multiplies losses. Fix the price or cost before increasing volume.
Is there an alternative with a higher return and lower risk?
Always compare against reducing churn and adjusting prices — usually the two most profitable and most ignored allocations.
How does this investment affect the consolidated ROIC?
Initiatives that require a lot of tied-up capital drag down ROIC even when absolute profit grows.
What is the stop criteria?
Define the indicator and timeframe that will end the experiment beforehand. Investment without stop criteria turns into fixed cost by inertia.
Who owns the number?
Every allocation needs an owner who reports the real result against the initial estimate in the next cycle.
Frequently Asked Questions
- What is the difference between profitability (lucrativeness) and return on investment?
- Profitability is the relationship between profit and revenue — it measures how much is left from each dollar sold. Return on investment is the relationship between profit and invested capital — it measures how much the applied money yields over time. A company can be profitable but yield poor returns if it required too much capital to generate that profit.
- What is NOPAT and why is it used in ROIC calculation?
- NOPAT is Net Operating Profit After Taxes. It reflects the profit generated exclusively by the operation after deducting direct taxes, but without interference from the financing structure (interest expenses or financial revenues). It is the indispensable numerator of ROIC because it allows evaluating the real return on invested capital.
- How to calculate ROI and ROIC?
- ROI is (gain obtained - investment) ÷ investment, usually annualized. ROIC is NOPAT (operating profit after taxes) divided by invested capital (equity plus interest-bearing debt, minus cash). ROIC is more rigorous because it isolates the operation's performance from the financing structure.
- What is a good CAC payback in SaaS?
- Under 12 months is considered healthy for B2B SaaS; between 12 and 18 months is acceptable with high net retention; above 24 months indicates growth is consuming cash faster than the base can return it.
- Does growing always reduce profitability?
- No. Growing reduces profitability in the short term when investment in acquisition, team, and infrastructure happens before the corresponding revenue. The problem is remaining in this state: if CAC payback doesn't shorten and contribution margin doesn't improve with scale, growth is destroying value.
Closing the loop: profit margin keeps the company standing this month; return on investment (profitability) decides whether it's worth continuing to put money into it over the coming years. Measure both, but choose where to invest by looking at the second.
Referências
- DAMODARAN, Aswath. Investment Valuation. It is a reference because it systematizes how return and risk combine in business valuation. Damodaran insists that returns only mean something when compared to the cost of capital employed — a 12% ROIC is excellent for a stable operation but insufficient for a startup raising expensive capital. Damodaran's database and materials
- BESSEMER VENTURE PARTNERS. Rule of 40. It is a reference because it popularized the main shorthand for reading between growth and profitability in SaaS: the sum of the growth rate and operating margin should be above 40%. The model highlights the trade-off that many founders treat as a moral choice when it's simply capital allocation. Read the Bessemer Atlas
- STRIPE. Unit Economics. It is a reference because it describes in operational language how to calculate revenue and cost per unit — customer, order, subscription — and why a company can grow total revenue while destroying value on each new sale. Stripe's unit economics guide
- SAAS CAPITAL. Private SaaS Company Benchmarks. It is a reference because it publishes annual data from private SaaS companies — growth, net retention, capital efficiency — allowing you to compare your operation with real peers instead of unicorns operating in another risk tier. Private SaaS benchmarks
- BRIGHAM, Eugene F.; EHRHARDT, Michael C. Financial Management. It is a reference because it presents the classic corporate finance tools — contribution margin, breakeven, payback, net present value — that support any cash reinvestment decision in companies of any size. Get to know the book
Discover the real profitability of your business
At Shinier Accelerator you structure your pricing, cash flow and projections with AI support and mentorship to reinvest where capital yields the most.
Get to know Shinier Accelerator