

Startup Budget in 2026: Burn Rate, Runway, and Scenario Planning to Avoid Cash Depletion
Startups rarely fail from lack of ideas. They fail from running out of cash in a month that was already predictable three quarters prior. This guide explains what a startup budget must reveal, how to calculate monthly burn rate and runway, separate CAPEX, OPEX, and variable costs, model conservative, base, and aggressive scenarios, deploy zero-based budgeting and rolling forecasts, and run a 1-hour monthly budget review.
There is a massive distinction between "having an expense spreadsheet" and "having a budget." A spreadsheet logs what has already transpired. A startup budget anticipates what will happen to cash reserves month by month under explicit assumptions — dictating when to cut, hire, raise capital, or pivot before decisions are forced by lack of options.
The Stripe Atlas accounting guide emphasizes an elementary yet frequently overlooked rule: rigorously separate accrual from cash accounting. A startup can close the month with signed contracts, invoices issued, and recognized revenue — yet lack funds to cover payroll because clients pay in 45 days while teams are paid on the 5th business day. A budget that ignores collection cycles is not a budget; it is mere wishful thinking.
This guide covers the full roadmap: what a budget must uncover, how to measure monthly burn rate and runway, how to segregate CAPEX, OPEX, and variable costs, how to build decision-driving scenarios, when to deploy zero-based budgeting and rolling forecasts, how to link financial plans to commercial goals and engineering bandwidth, plus a ready-to-use monthly review framework.
💡 The fatal mistake founders make: building an annual budget once with a single optimistic scenario, only checking bank balances when panicked. A budget is a navigation instrument — without monthly recalibration, it ceases to describe reality and merely describes the business you hoped you had.
What Must a Startup Budget Reveal?
An effective budget answers five questions without opening auxiliary sheets: how much cash enters and when; how much cash leaves and when; what is the projected month-end balance for the next twelve months; in which month does cash breach safety thresholds; and what operational lever must move today to extend that horizon.
The U.S. Small Business Administration breaks small business financial management into blocks equally applicable to tech startups: cash flow forecasting, working capital, receivables and payables control, pricing, and debt planning. None are inherently complex. Ventures collapse not from lack of exotic financial models — but from neglecting fundamentals executed with discipline.
Accrual vs. Cash Accounting
Two parallel perspectives. Accrual shows economic profitability; cash shows whether the venture survives to realize it. Startups that appear healthy on paper often expire in the timing gap between both ledgers.
Real Inflow and Outflow Timeline
Collection dates by customer, DSO (Days Sales Outstanding), taxes, payroll, benefits, bonuses, annual license renewals, and receivables factoring. The month where three annual vendor contracts collide must be visible twelve months in advance.
Gross and Net Burn Rate Monthly
Total disbursements regardless of collections, and net cash destroyed. A blended expenditure line obscures lumpy revenue cycles and misleads founders into relying on artificial averages.
Runway and the Decision Month
Saying 'we have eleven months' is insufficient. The budget must pinpoint the exact month cash drops below safety buffers and, back-calculating fundraising or restructuring lead times, reveal the ultimate deadline to execute.
Documented and Named Assumptions
ACV, sales cycles, conversion rates, churn, delinquency, vendor inflation, FX rates, and cloud scaling factors. Unstated assumptions cannot be audited, calibrated, or held accountable when targets miss.
Budget vs. Actual Variance Analysis
Horngren's variance analysis applied to daily operations: line by line, budget vs. actuals, variance in currency and percentage, plus a single-sentence rationale. Without this column, financial models never learn.
Quality stress test: ask a team member to determine, looking solely at the budget, in which month the company runs out of cash under the conservative scenario. If their answer requires founder explanation, the model is inadequate — it depends on your narrative, meaning no autonomous decisions can be made from it.
Ready to build your startup's budget with method instead of guesswork?
Within Shinier's platform, you engineer budgets, cash flows, pricing, and product roadmaps in unison: every commercial milestone maps to technical bandwidth, and every hire is immediately reflected in burn rate and projected runway.
For Founders Preserving Cash
Deploy our budgeting engines, cash flow trackers, and pricing models to visualize burn rate, runway, and multi-scenario forecasts in one unified hub.
For Enterprises & Software Houses
Need to connect financial budgets, team allocation, and project margins with auditable metrics? Consult with the Shinier team on modern governance models.
How to Calculate Monthly Burn Rate and Runway
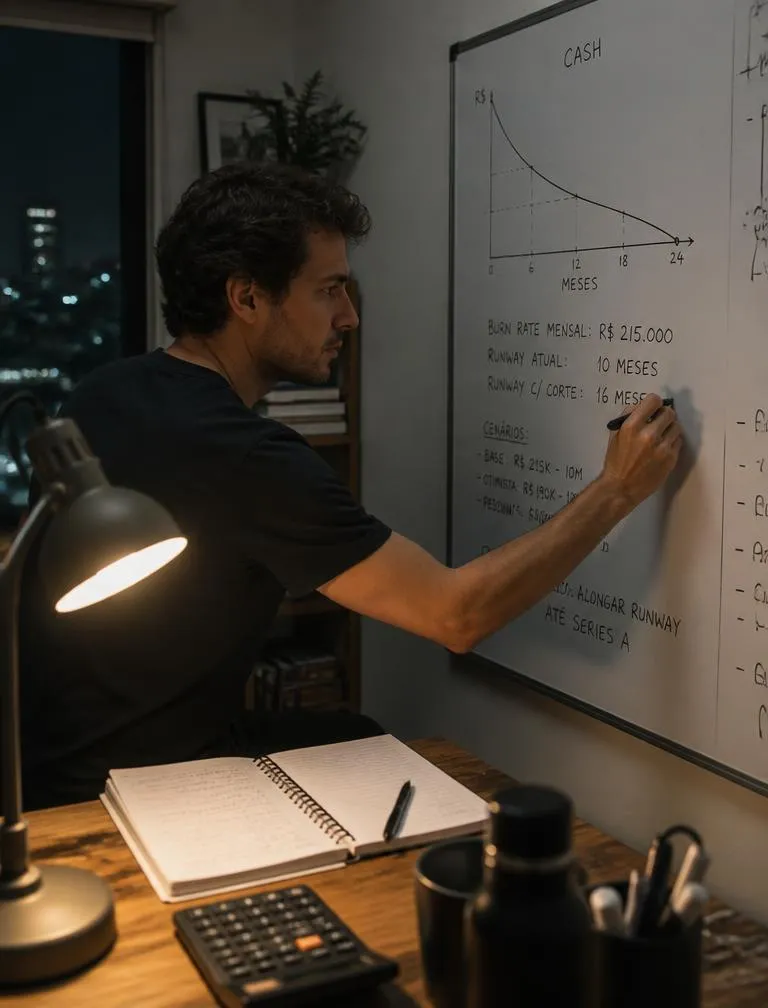
Burn rate is the velocity at which an enterprise burns cash. Runway is how long that velocity permits continued existence. Both calculations take two lines, and their apparent simplicity is why they are so often flawed — usually through excessively long averages or forgetting non-monthly lump expenses.
Gross Burn Rate
Sum of all cash outflows in a month: salaries, payroll taxes, founder drawings, suppliers, cloud hosting, tools, taxes, marketing, accounting, rent, and debt service.
Gross Burn = total monthly cash outflows
Net Burn Rate
The net cash consumed after deducting actual collections received — cash in the bank, not merely billed receivables.
Net Burn = cash outflows − cash inflows
Runway
Months remaining until reserves hit zero at the current expenditure pace. Use the 3-month trailing average, never a 12-month average — prolonged historical windows mask recent deterioration.
Runway = cash reserves ÷ 3-month average net burn
Complete Numerical Example
A B2B SaaS startup maintains $1,200,000 in cash. Over the past three months, cash outflows were $310,000, $325,000, and $340,000; cash collections were $150,000, $160,000, and $155,000. Average gross burn is $325,000 and average net burn is $170,000. Runway equals $1,200,000 ÷ $170,000 ≈ 7 months.
Seven months feels manageable until factoring in two recurring realities: monthly burn is growing by 5% in this trajectory, and equity fundraising requires four to six months from initial intro to cleared funds. The company does not have seven months of deliberation — it has at most one month. That is the difference between calculating runway and managing runway.
Distortions that bias runway metrics: amortizing annual software licenses improperly, ignoring accrued vacation and statutory bonuses, treating billed invoices as cash, recording receivables advances as organic revenue, and failing to deduct committed liabilities payable within thirty days.
How to Separate CAPEX, OPEX, and Variable Costs
Segregating expense types might seem like accounting semantics, but it governs three critical decisions: what can be cut within 30 days, what exits reserves only once, and what scales automatically with sales volume. Horngren demonstrates that budgeting without proper cost classification leads to disastrous decisions even when arithmetic is accurate.
CAPEX
Capital expenditures on long-term assets: hardware, machinery, facilities, and eligible capitalized software development. Depletes cash upfront while impacting P&L gradually via depreciation or amortization. In tech startups, oversized CAPEX is the fastest way to trade months of runway for idle capacity.
OPEX
Operational overhead: salaries, SaaS tooling, accounting, lease, baseline infrastructure, ongoing marketing. This is the structural burn engine. The key question for each line item is not 'how much is it', but 'how many days to terminate this without stopping delivery' — determining your operational agility.
Variable Costs
Scale directly with delivery volume: payment gateway fees, compute-on-demand, tier-based support, sales commissions, SMS/email relays, or API tokens. These turn top-line expansion into operational bleeding if pricing was established before factoring per-unit cost of delivery.
Cloud: The Line Item Requiring FinOps Rigor
For software startups, cloud hosting is hybrid OPEX and variable cost — and consistently the biggest variance shock. The FinOps Framework provides a 3-phase governance loop: Inform (cost transparency per microservice and tag), Optimize (reservations, rightsizing, decommissioning idle clusters, storage tiering), and Operate (embedding cost consciousness directly into engineering rituals rather than reactive quarterly audits).
The metric that dictates viability is infrastructure unit cost — cloud cost per active customer, per transaction, or per million API hits. If this metric expands alongside revenue, you do not have economies of scale; you have architectural debt paid monthly in burning cash.
How to Construct Conservative, Base, and Aggressive Scenarios
Scenario modeling is not cloning spreadsheets with altered growth percentages. Each scenario represents a coherent hypothesis paired with an objective activation trigger and pre-agreed action plans. The value is not predicting destiny — it is having decisions locked before panic sets in, while strategic leeway still exists.
Conservative — The Survival Scenario
Revenue 30% to 40% below target, sales cycles 50% longer, higher payment defaults, and zero venture funding. Here you establish the objective trigger — e.g., two consecutive months under 70% quota — and the exact cutback sequence, from lowest to highest organizational friction, assigned to owners with strict deadlines.
| Assumption | Conservative | Base | Aggressive |
|---|---|---|---|
| New contracts/month | 2 | 4 | 7 |
| Sales cycle | 120 days | 80 days | 60 days |
| Monthly churn | 3.5% | 2.0% | 1.2% |
| Hires in semester | 0 | 2 | 5 |
| Projected runway | 14 months | 11 months | 8 months |
Notice the counter-intuitive metric in the bottom row: the aggressive scenario holds the shortest runway. Accelerated growth requires front-loading payroll and working capital before cash collections stabilize. This is why the Bessemer Atlas insists on balancing growth with capital efficiency — the Rule of 40 exists to prevent praising velocity paid for with cash destruction.
When to Deploy Zero-Based Budgeting and Rolling Forecasts
Complementary frameworks with distinct mandates. Zero-based budgeting (ZBB) is a periodic reconstruction milestone; rolling forecasts represent a continuous projection cadence. ZBB alone produces blunt, directionless cuts; rolling forecasts alone entrench organizational inertia under updated numbers.
Zero-Based Budgeting (ZBB)
Instead of indexing prior year expenses with inflation multipliers, every cost center resets to zero and must justify its business value for the forthcoming cycle. It ruthlessly uncovers forgotten SaaS seats, redundant tooling, auto-renewed vendor pacts, and headcount inflation.
- • Deploy at fiscal year boundaries or major funding milestone shifts.
- • Deploy ahead of venture capital rounds to avoid funding overhead with dilution.
- • Deploy when burn outpaces revenue growth across two consecutive quarters.
- • Avoid monthly execution: coordination drag outweighs financial savings.
Rolling Forecast
At each monthly close, actuals replace projections and a new month is appended to the horizon, maintaining an ongoing 12-month forward radar. Budgets evolve from static, decaying annual binders into dynamic planning instruments.
- • Constant 12-month forward horizon, updated every month.
- • Calibrate parameters rather than rebuilding financial models.
- • Every revision documents variance figures and single-sentence explanations.
- • Feeds the continuous recalculation of all three planning scenarios.
The winning startup cadence: Zero-based budgeting annually or at structural inflection points; rolling forecasts monthly; scenario recalibration quarterly. Three distinct rhythms addressing three essential questions: what should we spend, what will we spend, and how do we pivot when conditions shift.
Connecting Budgets to Commercial Milestones and Engineering Bandwidth
Budgets disintegrate when treated as isolated finance department artifacts. They only succeed when three mechanisms remain synchronized: commercial quotas drive throughput volume, volume dictates technical engineering capacity, and capacity determines cost structures — which loop back into the budget to test feasibility before sign-off.
Consider a software development firm: selling 40% more projects demands available engineering hours. If team utilization is already at 85%, zero buffer exists. Delivering more requires hiring two months prior to contract execution, funded with uncollected capital, or suffering delivery delays that trigger customer churn. Both outcomes surface in a unified budget; neither appears on an isolated sales goal sheet.
Translate revenue targets into delivery units
Count required contracts, software licenses, projects, or transactional events. Revenue is an outcome; delivery volume is what consumes capacity and generates variable costs.
Convert units into hours and team headcount
Apply empirical delivery cycle times and a sustainable utilization rate (70% to 80%). Budgeting with 100% capacity is planning for missed deadlines.
Position hiring cycles on the correct timeline
Sourcing, hiring, and productivity ramp take two to four months. Overhead hits the budget well before corresponding customer billings.
Aggregate variable delivery costs that scale proportionally
Hosting bandwidth, customer support, sales compensation, gateway fees, and user licenses. Growth introduces proportional cost — budgets must quantify it.
Validate runway solvency before approving aggressive targets
If an aggressive revenue target compresses runway below safety buffers without committed capital injections, the target is reckless ambition, not an approved plan.
Founder Blueprint for Monthly Budget Reviews
Sixty minutes every month, during the same week, with fixed agendas and clear ownership. Budget reviews are not designed to admire spreadsheets: their sole purpose is leaving with recorded decisions, assigned owners, and hard deadlines.

10 min — Cash and Runway
Current cash balance, monthly gross and net burn, updated runway, and projected decision milestone. Always the opening item, never postponed.
15 min — Budget vs. Actuals
Exclusively inspect line items with variance beyond predefined limits (e.g., >10% or $1,000). Every variance requires a concise single-sentence root cause.
10 min — Pipeline & Collections
Invoiced volume versus actual funds collected, DSO, and bad debt. Uncollected billings do not qualify as revenue in this forum.
10 min — Assumptions & Rolling Forecast
Roll forward the 12-month horizon replacing the closed month, update shifting assumptions, and assess whether any scenario pivot trigger was hit.
15 min — Operational Decisions
Authorize, postpone, eliminate, renegotiate, factor receivables, or initiate investor talks. Every action item leaves with an owner, deadline, and runway delta.
Four Red Flags Requiring Immediate Same-Day Action
- • Runway falls below six months without an active, advanced fundraise.
- • Monthly burn escalates for three straight months despite flat revenues.
- • Days Sales Outstanding (DSO) expands while vendor payment terms compress.
- • Per-unit delivery costs increase while customer volume grows.
Frequently Asked Questions
- What is the distinction between gross burn rate and net burn rate?
- Gross burn rate measures total monthly cash outflows regardless of inflows. Net burn rate represents the difference between outflows and actual collections — indicating the net cash destroyed. Runway calculations must use net burn, but tracking gross burn is vital to gauge vulnerability to revenue volatility.
- How many months of runway should a startup maintain?
- Standard venture guidelines recommend never operating with under six months of reserves, and kicking off any fundraising process with at least twelve months of runway. Below six months, founders surrender negotiating leverage — accepting punitive valuations, adverse customer contracts, and poor vendor terms due to lack of time.
- Is zero-based budgeting viable for early-stage startups?
- Yes, and it is often more effective in early startups than in large conglomerates because operational line items can be reconstructed in a few hours. The value lies in the intellectual exercise: having to justify every cost eliminates orphan subscriptions, duplicate SaaS seats, and obsolete contracts.
- How frequently should a startup update its budget?
- Monthly with an efficient, structured budget-versus-actuals review, and quarterly with a comprehensive recalibration of core assumptions and scenarios. Appending a rolling forward horizon every month ensures the annual model never decays into fiction by March.
Final takeaways: A budget does not exist to predict the future with prophetic precision — it exists to buy decision time. The founder who knows, every single week, their precise cash burn, remaining runway, and actionable levers under each scenario, negotiates with leverage against investors, enterprise clients, and suppliers. Those who discover cash shortfalls on bank statements have already surrendered the budget's greatest asset: strategic foresight.
Referências
- STRIPE ATLAS. Startup Accounting Guide. Essential founder reference explaining baseline financial governance from inception: personal versus business entity separation, accrual vs. cash mechanisms, recurring revenue recognition, and due diligence reporting packages. Read the Stripe Atlas Accounting Guide
- FINOPS FOUNDATION. FinOps Framework. Established standard structuring cloud financial operations into Inform, Optimize, and Operate phases, preventing engineering infrastructure costs from outstripping top-line software revenue. Consult the FinOps Framework
- BESSEMER VENTURE PARTNERS. Atlas. Benchmark directory compiling SaaS financial efficiency metrics — Rule of 40, Magic Number, Net Revenue Retention, and stage-specific burn multiple guidelines. Access the Bessemer Atlas
- U.S. SMALL BUSINESS ADMINISTRATION. Manage Your Finances. Practical guide covering core SMB financial stewardship: cash flow projections, working capital management, accounts receivable control, pricing, and credit lines. View SBA Financial Management Guide
- HORNGREN, Charles T. Cost Accounting. Seminal corporate accounting text formalizing fixed vs. variable cost behavior, activity-based costing, budget-vs-actual variance analysis, and flexible budgeting foundations. Examine Horngren's Cost Accounting Text
Build Your Startup's Budget with Discipline and Precision
In the Shinier Accelerator, you structure financial budgets, cash flow projections, unit pricing, commercial milestones, and execution roadmaps alongside seasoned founders — from net burn control to investment-grade runway planning.
Explore Shinier Accelerator